A Practical Guide to Navigating Nigeria’s Diaspora Real Estate Market
INTRODUCTION
For many Nigerians living abroad, investing in property back home is more than a financial decision. It can be a way to build long-term wealth, secure a future home, create rental income, support family, or maintain a connection to Nigeria.
Nigeria’s real estate market offers opportunities across residential properties, land, apartments, commercial properties, and housing developments. However, investing from thousands of kilometres away comes with unique challenges. Distance can make it difficult to inspect a property, verify ownership and title documents, monitor construction, or determine whether the people handling the transaction can be trusted.
The good news is that living in the diaspora does not mean you have to invest blindly. With proper due diligence, reliable professional representation, secure payment arrangements, and a clear understanding of property documentation, Nigerians abroad can significantly reduce the risks associated with investing in Nigerian real estate.
This guide explores some of the key considerations diaspora Nigerians should understand before committing their money to property in Nigeria.
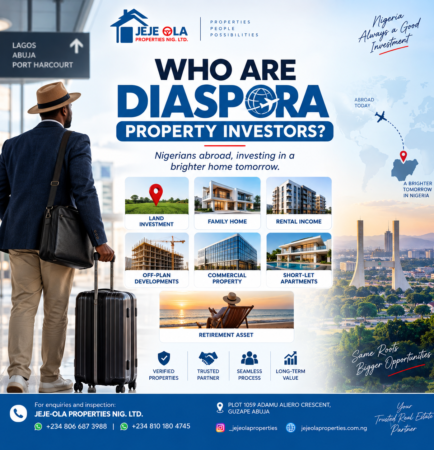
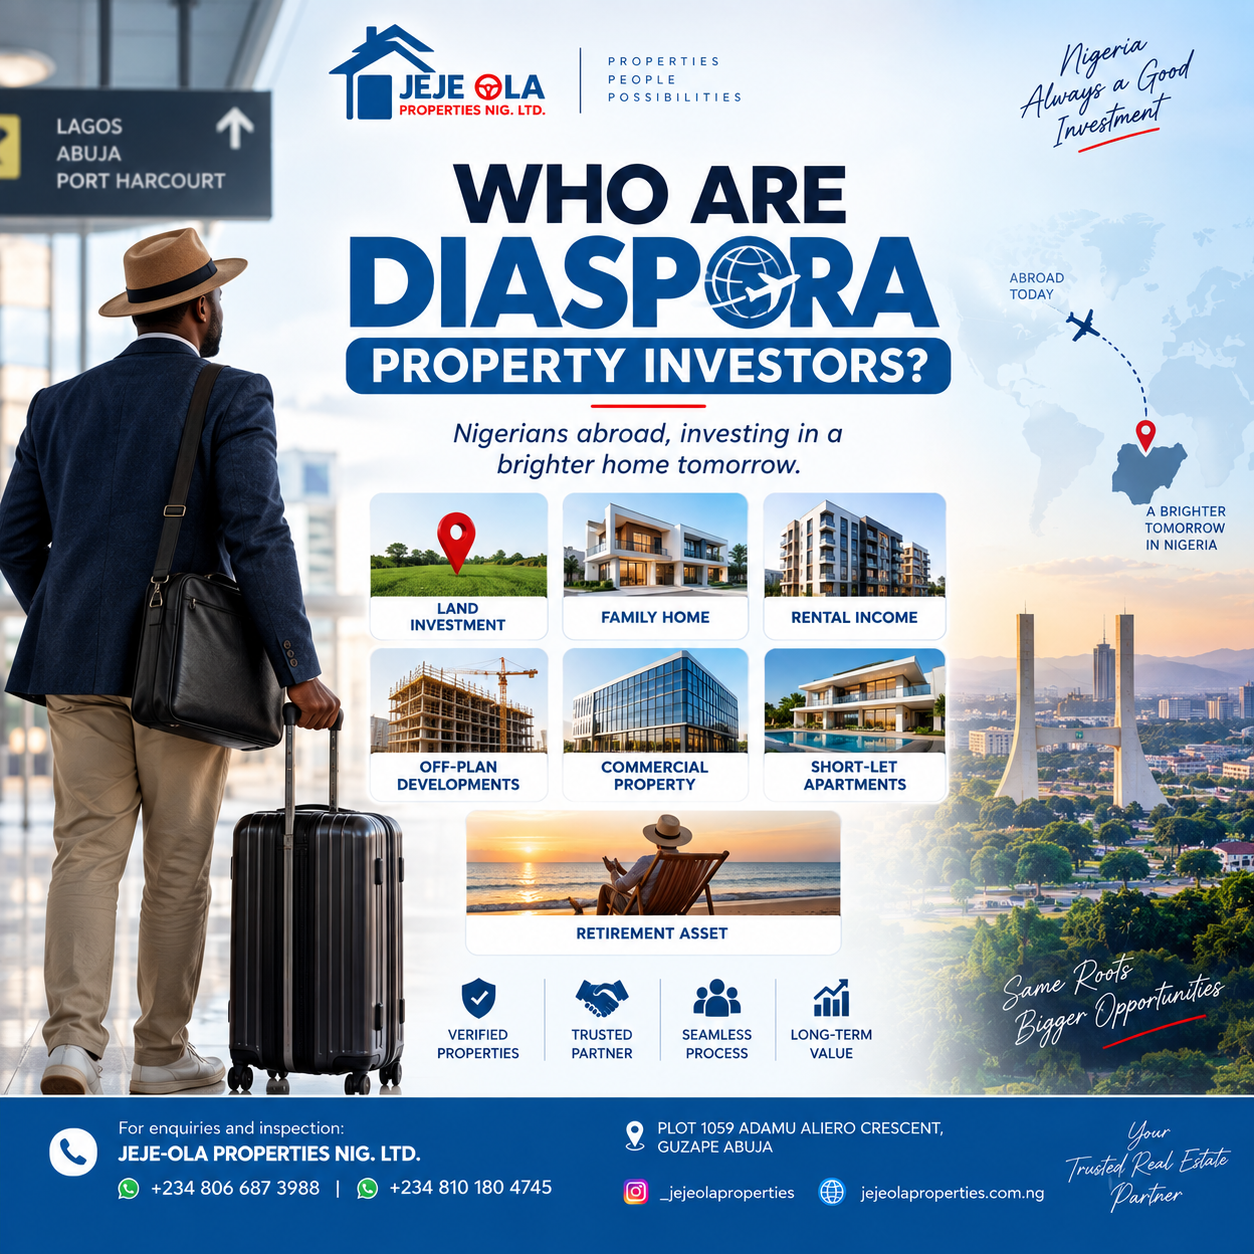
WHO ARE DIASPORA PROPERTY INVESTORS?
Diaspora property investors are Nigerians living outside the country who want to acquire, develop, or invest in real estate in Nigeria.
Their investment goals may vary. Some may want to buy land for future development, build a family home, purchasing apartments for rental income, acquire property for resale, invest in off-plan developments, purchase commercial property, develop short-let apartments, or secure real estate as a long-term retirement asset.
While their motivations may differ, one principle remains the same: every property investment should be properly verified before money changes hands.
WHY PROPERTY INVESTMENT IN NIGERIA APPEALS TO NIGERIANS ABROAD
1. Building Long-Term Wealth
Real estate is often viewed as a long-term wealth-building asset. Land and properly selected properties may appreciate in value over time, although appreciation and investment returns are never guaranteed.
2. Generating Rental Income
A properly located residential or commercial property can generate rental income. However, rental income should never be assumed. Demand, maintenance costs, service charges, property management, and location can all affect the actual return.
3. Preparing for the Future
Some Nigerians abroad invest in property because they intend to return to Nigeria eventually. Buying land or a house in advance may allow them to secure a property in their preferred location and potentially benefit from future increases in property values.
4. Diversifying an Investment Portfolio
Property can form part of a broader investment portfolio. Investors should consider how Nigerian real estate fits alongside their other investments, financial obligations, and long-term financial goals in their country of residence.
THE BIGGEST RISKS DIASPORA INVESTORS FACE
Investing in Nigerian property from abroad comes with risks that can be more difficult to identify or manage from a distance. Diaspora investors may have to rely heavily on information provided by agents, relatives, developers, friends, or other representatives. While many of these individuals may be acting in good faith, the distance between the investor and the property can create opportunities for misrepresentation, fraud, or poor oversight.
1. Misleading or Fake Property Listings
A property advertised online may not belong to the person advertising it, or the information provided about the property may be inaccurate. Attractive photographs, videos, and professionally designed flyers do not establish ownership or confirm that the property is available for sale.
2. Fake or Defective Property Documents
A seller may present documents that appear legitimate but have not been properly verified. Documents such as survey plans, deeds, allocation papers, and Certificates of Occupancy should be independently examined and verified where applicable rather than accepted at face value.
3. Multiple Sales or Competing Claims
One serious risk in Nigerian real estate is purchasing a property that has already been sold, transferred, pledged, or otherwise committed to another person. Proper title searches and legal due diligence are therefore essential before making a substantial payment.
4. Family or Community Disputes
A property may be subject to disputes involving family members, communities, previous owners, or other claimants. These disputes can affect the buyer’s ability to obtain or enjoy valid and undisputed ownership of the property.
5. Unauthorised or Poorly Defined Representation
Diaspora investors sometimes rely on relatives, friends, agents, or other representatives to act on their behalf. Giving someone authority to handle a transaction without clearly defining the scope of that authority, their responsibilities, and the limits of their powers can expose the investor to significant risk.
6. Construction and Project Management Risks
For investors developing property from abroad, limited physical oversight can make it more difficult to monitor construction. Funds may be released without adequate documentation, independent supervision, proper progress reporting, or confirmation that work has been completed as agreed.
HOW TO SAFELY INVEST IN NIGERIAN PROPERTY FROM ABROAD
1. Define Your Investment Objective First
Before searching for a property, determine exactly what you want to achieve. Are you buying a home for personal use, seeking rental income, investing for potential land appreciation, planning for retirement, or purchasing for resale? Your objective should influence the location, property type, budget, and expected holding period.
2. Research the Location Carefully
Do not buy simply because a property is advertised as being in a “hot area.” Consider road accessibility, security, infrastructure, electricity, water supply, drainage and flooding risks, proximity to major roads, schools and hospitals, commercial activity, employment centres, population growth, rental demand, and planned infrastructure projects.
Where possible, conduct your own research and obtain independent information about the area rather than relying solely on the seller or agent’s description.
3. Verify the Property, Title and Survey
Do not assume that a document is genuine, valid, or sufficient to establish title simply because you have received a copy. Depending on the nature and location of the property, relevant documents may include a Certificate of Occupancy, Deed of Assignment, registered survey plan, Governor’s Consent, allocation letter, Deed of Conveyance, Power of Attorney, purchase agreement, and previous title documents.
Before making a major payment, instruct a qualified property lawyer to conduct appropriate searches and legal due diligence. The investigation should, as applicable, help establish who holds the relevant interest in the property, whether the seller has the authority to transfer it, whether th property has previously been transferred, whether there are registered mortgages or other encumbrances, whether there are known disputes or competing claims, and whether the property is affected by government acquisition or other restrictions. The specific searches required will depend on the location and nature of the property.
The survey should also be independently verified. A survey plan can help identify the location, boundaries, dimensions, and coordinates of a parcel of land. An appropriately qualified surveyor can verify whether the land being offered corresponds with the survey information and identify potential issues such as encroachment, boundary discrepancies, or other location-related concerns.
4. Use an Independent Property Lawyer and Proper Representation
For a diaspora investor, having an independent property lawyer engaged to represent your interests rather than those of the seller or developer is one of the most important safeguards. A property lawyer can assist with title verification, legal due diligence, land-registry searches, contract review, verification of the seller’s authority, preparation or review of deeds and powers of attorney, identification of legal risks, and ensuring that the transaction is properly documented.
If you need someone to represent you physically in Nigeria, use a properly prepared Power of Attorney that clearly defines what the representative is authorised to do and the limits of that authority. Avoid giving unnecessarily broad powers, particularly where the representative may be involved in receiving funds, signing transaction documents, selling or transferring property, or dealing with other significant assets on your behalf.
5. Arrange an Independent Property Inspection
Being abroad does not mean you have to rely solely on photographs or WhatsApp videos. If you cannot inspect the property yourself, arrange for a trusted and independent person or professional to visit the property physically on your behalf.
The inspection should verify the property’s exact location, access roads, boundaries, surrounding properties, drainage, utilities, signs of occupation, and possible encroachment. Where possible, request dated photographs, videos, location details, and a written inspection report so you can independently assess what was found. Avoid relying solely on an inspection conducted by the seller, developer, or agent.
6. Verify the Developer Before Buying Off-Plan Property
Before committing to an off-plan development, investigate the developer’s track record, previously completed projects, corporate registration, ownership or interest in the development land, applicable planning and development approvals, construction timeline, payment structure, refund provisions, contractual terms, service charges, and handover conditions.
Do not rely solely on promotional materials or verbal assurances. The developer and the underlying project should be independently assessed before significant funds are committed.
7. Secure Your Payment Process
Payment procedures should be clear, documented, and consistent with the transaction agreement. Where possible, payments should be made through legitimate, traceable channels and to the appropriate account identified in the contractual documentation.
Be particularly cautious about last-minute changes to payment details, requests to transfer funds to unrelated personal accounts, or pressure to make immediate payments before completing due diligence.
8. Understand the Full Cost of the Investment
The advertised property price may not represent the total amount you will spend. Depending on the transaction, you may need to budget for legal fees, survey fees, registration, stamp duties, government charges, consent fees, agency fees, development levies, service charges, construction costs, property management, maintenance, and applicable taxes.
Ask for a clear breakdown of the expected costs before committing to the transaction.
9. Keep Your Documentation Organised
Create a secure digital and physical record of the transaction. Depending on the investment, this may include the purchase agreement, receipts, survey plan, Deed of Assignment, Certificate of Occupancy or other title documents, allocation documents, government correspondence, building approvals, payment records, inspection reports, photographs, and legal due-diligence reports.
Keep backup copies in a secure location that you can access even when you are outside Nigeria.
10. Document and Secure the Transaction
Never rely solely on verbal promises. The transaction should be supported by appropriate written documentation clearly setting out the parties, property description, purchase price, payment schedule, respective responsibilities, documents to be provided, completion or handover arrangements, default and applicable refund provisions, and dispute-resolution arrangements. Have the agreement reviewed by your lawyer before signing or making substantial payments.
Keep a secure digital and physical record of the transaction agreements, receipts, survey plan, title documents, allocation documents, government correspondence, building approvals, payment records, inspection reports, photographs, and legal due-diligence reports. Keep backup copies in a secure location that you can access from abroad.
11. Have a Property Management Plan
If you live abroad, decide in advance who will collect rent, pay bills, handle repairs, monitor tenants, inspect the property, pay service charges, respond to emergencies, and provide financial reports.
If you engage a property management company or individual, clearly document their responsibilities, authority, fees, reporting obligations, and procedures for handling rental income and expenses.
RED FLAGS EVERY DIASPORA INVESTOR SHOULD WATCH FOR
Certain statements or behaviours should immediately make a diaspora investor pause and ask more questions. Be cautious when you hear things such as:
- “You don’t need a lawyer.”
- “Just pay first; the documents will come later.”
- “This offer expires today.”
- “Don’t worry about the survey.”
- “Everyone is buying here.”
- “Send the money to my personal account.”
- “You don’t need to inspect the land.”
- “I am a trusted person, so you don’t need documentation.”
These statements do not automatically mean that a transaction is fraudulent. However, they are warning signs that should prompt you to slow down, verify the information independently, and complete your due diligence before committing your money.
A SAFER DIASPORA PROPERTY INVESTMENT PROCESS
The following checklist summarises the key steps diaspora investors should take before and after committing to a property investment in Nigeria:
STEP 1 — Define your goal: Know whether you are buying for residence, rental income, appreciation, retirement, resale, or development.
STEP 2 — Research the location: Consider infrastructure, demand, security, accessibility, flooding risks, and development patterns.
STEP 3 — Investigate the seller or developer: Verify their identity, authority, ownership or interest in the property, and track record.
STEP 4 — Engage independent professionals: Where appropriate, engage an independent property lawyer, qualified surveyor, and estate surveyor/valuer.
STEP 5 — Verify the property and title: Conduct the necessary searches and due diligence with the relevant authorities and professionals.
STEP 6 — Inspect the property: Physically inspect it yourself or arrange for an independent professional to inspect it on your behalf.
STEP 7 — Review the transaction documents: Understand the agreement, payment terms, obligations, and other relevant documents before signing.
STEP 8 — Make secure payments: Use traceable and properly documented payment channels and verify payment instructions before transferring funds.
STEP 9 — Complete the documentation and registration: Ensure the necessary transfer, perfection, and registration processes are properly completed.
STEP 10 — Manage the asset: Put appropriate systems in place for property management, maintenance, rent collection, and financial reporting.
Golden Rule: The farther you are from the property, the closer you should be to the details.
FINAL THOUGHTS
For Nigerians abroad, investing in property back home can be a valuable opportunity to build wealth, secure a future home, or generate income. But distance makes proper due diligence, documentation, professional advice, and effective management even more important.
The goal should not simply be to own property in Nigeria, but to own properly verified property through a properly documented and structured transaction.
Your money worked hard to get home. Make sure your investment does too.